Home Pre Launches Residential Properties Commercial Properties Black Circle Refer a Client Why Us Meet Our Team Awards & Recognitions Blog Call Us Terms & Conditions

+91 636 44 66 801  ·  Bengaluru · Hyderabad · Gurgaon · Dubai

Noida · Market Trends ·

Noida 2026: the airport is open, and the price gap with Gurgaon is the whole trade

Noida trades roughly 26% below Gurugram with a new international airport on its southern edge. That discount is either the opportunity or the warning, depending on which sector you buy.

BNoida 2026: the airport is open, and the price gap with Gurgaon is the whole trade

The structural fact about Noida in 2026 is a price gap. ANAROCK's Santhosh Kumar puts Gurugram's average at about ₹13,000 per square foot against Noida's ₹10,300 — roughly 26% — with Greater Noida at ₹7,500 and the Yamuna Expressway authority region at close to half Gurugram's level. Noida now has an operating international airport on its southern edge, which Gurugram does not. The question every buyer here is implicitly answering is whether that gap is a mispricing or an accurate reading of two different markets.

The case for mispricing rests on infrastructure that has actually been delivered rather than announced. Noida International Airport at Jewar has moved from construction to operation, the Noida Metro extension and the Ghaziabad–Jewar Regional Rapid Transit System are both progressing, and the Yamuna Expressway already connects the belt to Agra and the wider corridor. Colliers projects values in the Yeida region rising 28% for plots and 22% for apartments over the next two years. Yeida apartment pricing has gone from about ₹3,200 per square foot in 2020 to roughly ₹9,600 in 2025, and Praveen Jain of NAREDCO puts land values in the broader Jewar influence zone up nearly 40% over five years.

The case against is supply. ANAROCK counts more than 52,000 residential units launched across Noida, Greater Noida and Yeida between 2022 and 2025 — 32,179 of them in Greater Noida alone, against 11,312 in Noida proper and 8,544 in Yeida. That is a great deal of inventory chasing an employment base that is still being built. The 450,000-plus jobs attributed to the upcoming technology and film hubs are a projection, not a payroll, and buyers should treat them accordingly.

Those two readings resolve differently by sector, which is why the city average is close to useless here. Noida proper — the sectors along the Noida–Greater Noida Expressway, where Grade A office stock has grown around 20% — is an employment-led market with existing tenants and a functioning resale market. Greater Noida and Yeida are infrastructure-led bets where the asset is the land and the catalyst is the airport, and where the 32,179-unit launch figure should temper any assumption about near-term price discovery.

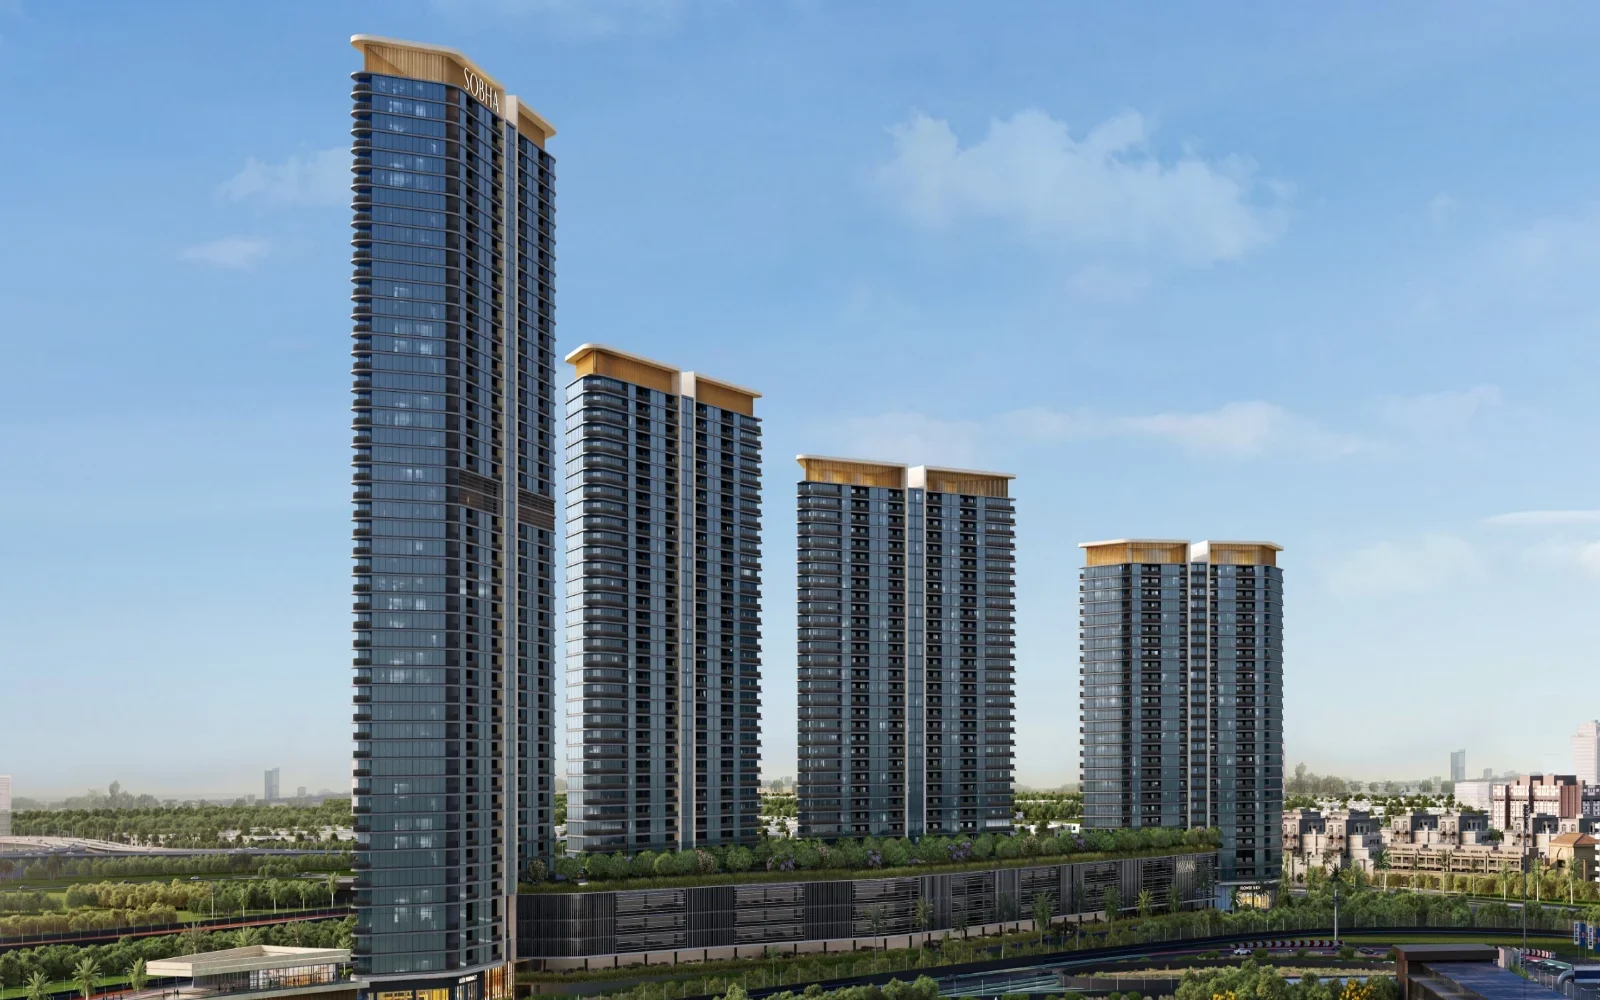
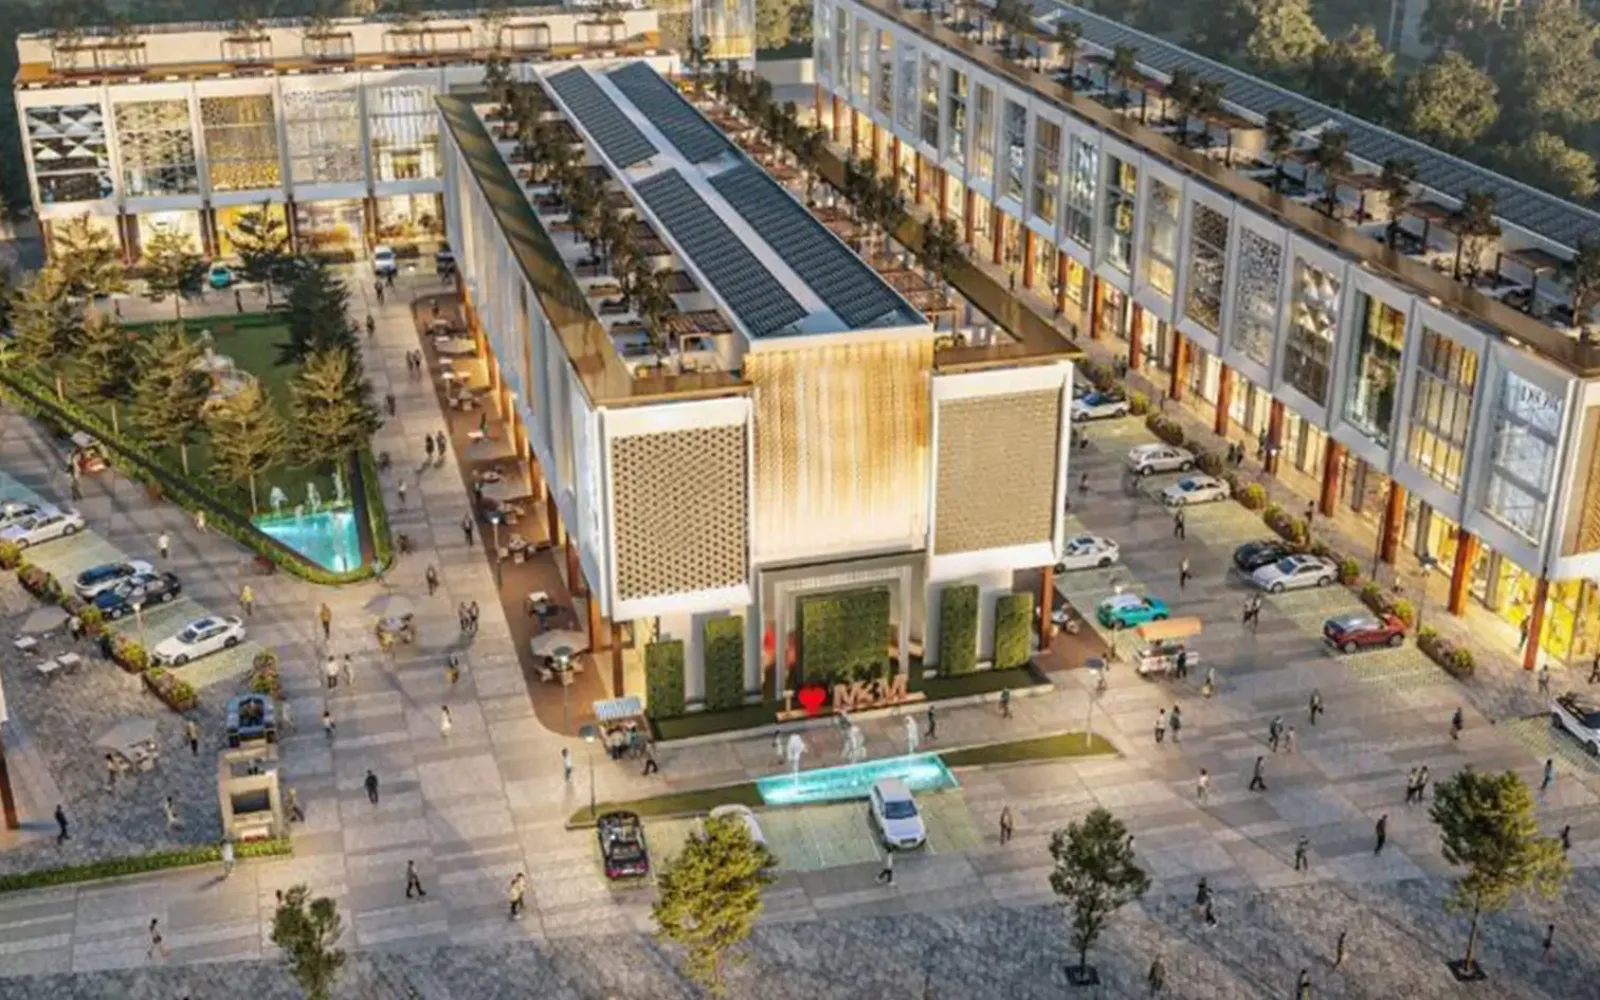
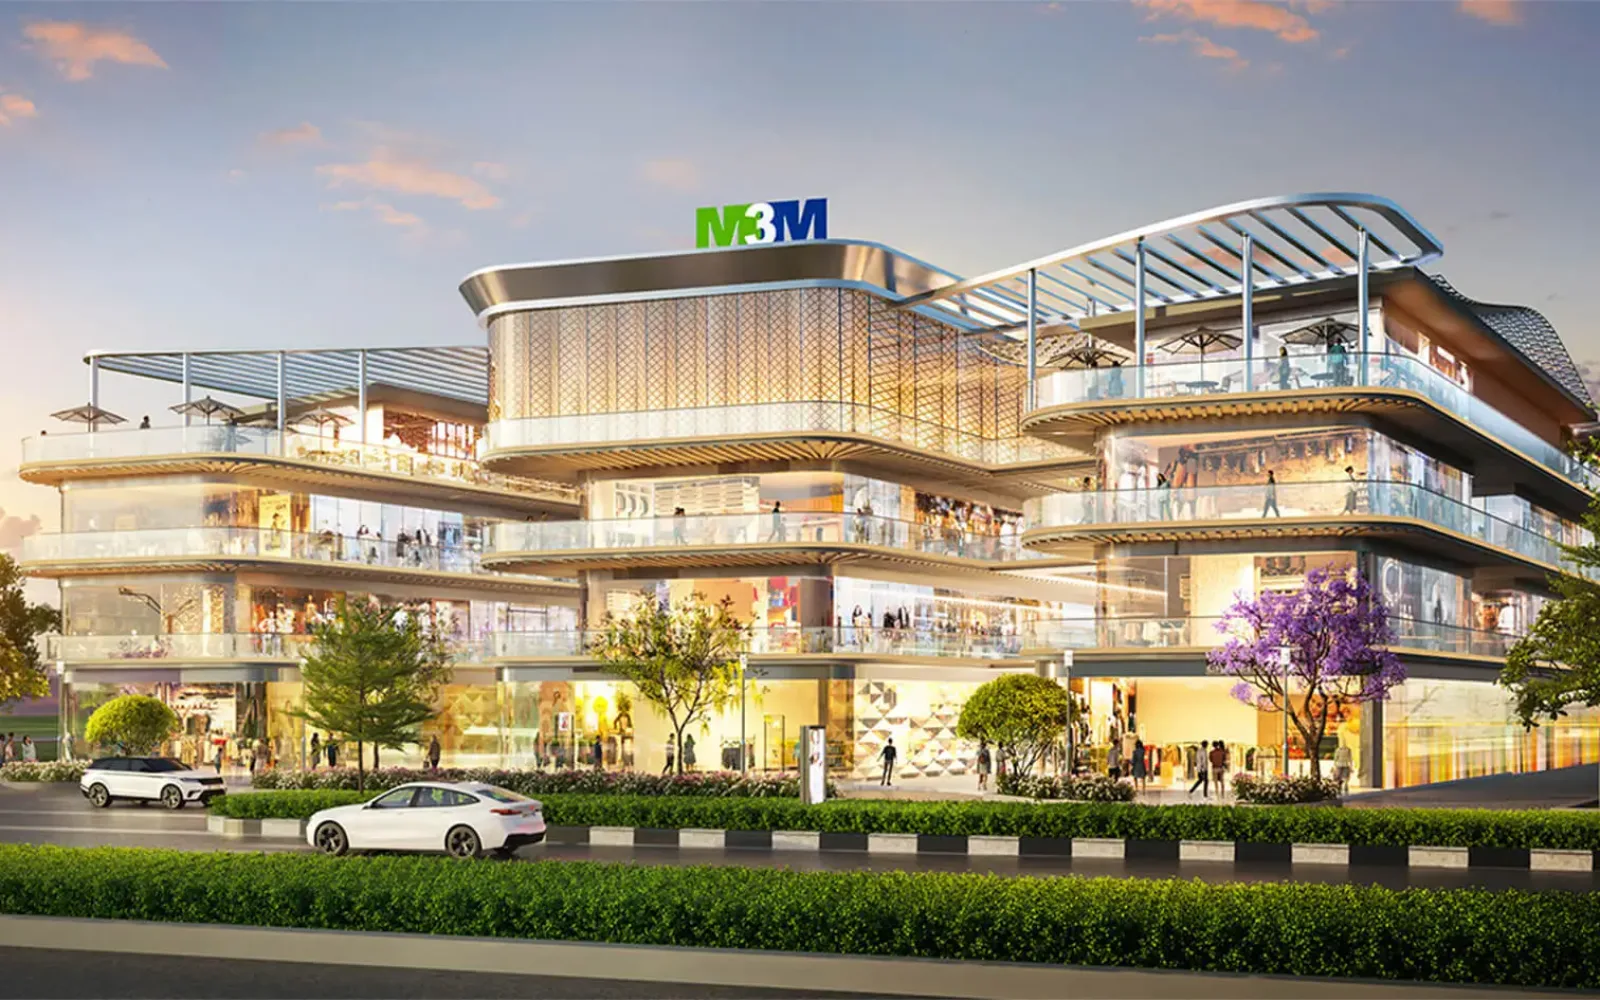
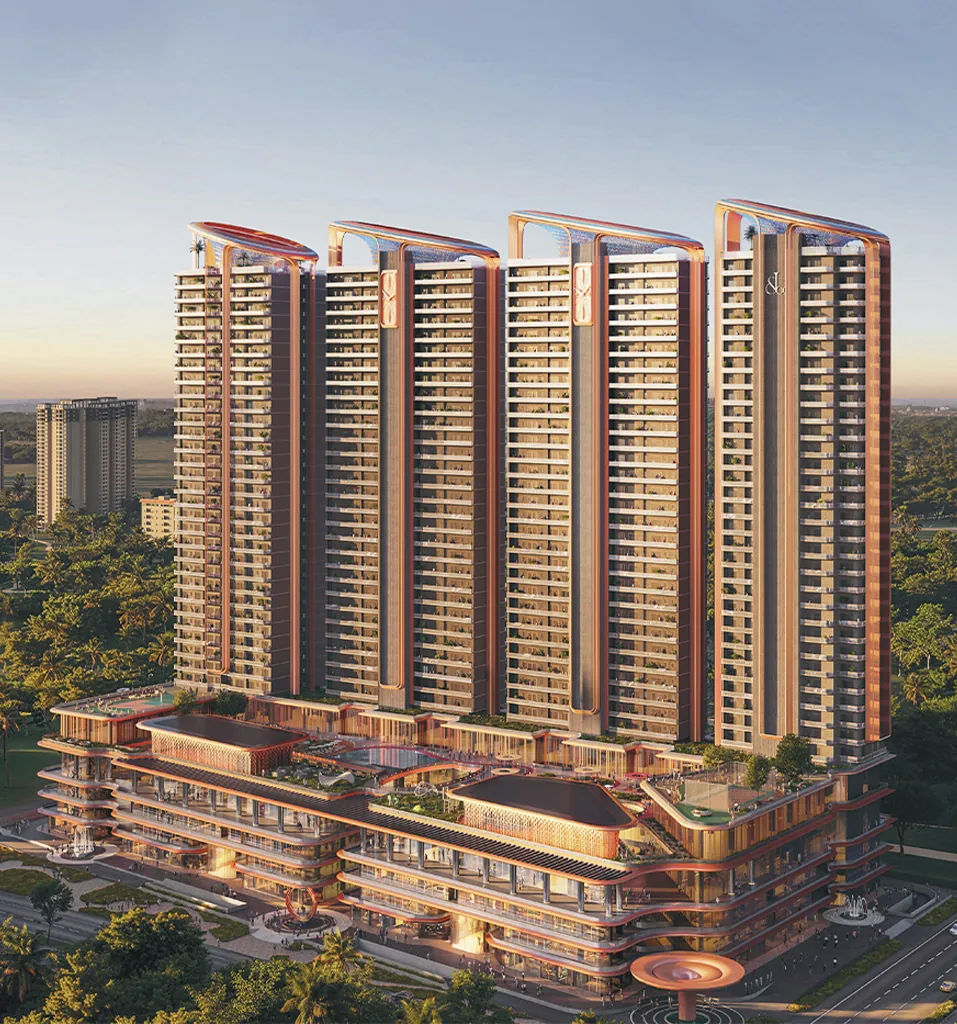
Premium supply in Noida proper remains thin, which is the part most buyers underestimate. M3M Jacob & Co Residences in Sector 97 is a deliberate test of that scarcity — roughly six acres, four towers, only 250 residences, from 2,500 square foot three-bedroom homes to 6,400 square foot five-bedroom formats, on the premise that low-density branded stock on the Expressway is structurally undersupplied. Whether that premise holds is the single most interesting question in the Noida market right now.

Our read: the Gurgaon discount is justified for Greater Noida and Yeida, where you are underwriting a jobs story that has not arrived, and harder to justify for established Expressway sectors with existing office absorption and an airport that now cuts the travel equation materially. If you are buying for a 2030-plus horizon in the Jewar influence zone, size the position as a land bet and accept the illiquidity. If you are buying to live in and let, stay north, in the sectors where the tenants already are.

One practical caution. Most of the headline appreciation figures circulating for the Jewar belt are consultant forecasts or developer estimates rather than registered transaction data, and they are usually quoted without that qualification. Before committing, ask for comparable registered sale deeds in the same sector from the last six months. In a corridor moving this fast, that is the only number that is not a projection.

Projects in this article

Weighing a purchase in this segment? A senior advisor will walk you through the numbers privately.

Keep reading
Gurgaon · Market Trends

Gurgaon's circle rates changed on 1 April 2026 — what you actually pay at registry

About half of Gurgaon's notified neighbourhoods saw no change at all. The ones that moved, moved hard — and the buyers it hits are not the ones you would expect.

Gurgaon's collector rates — what everyone calls circle rates — were revised with effect from 1 April 2026, the third revision Haryana has notified since the 2024 state elections. Most locales moved 15 to 30%. Some fast-developing zones went up by as much as 75%. And roughly 51% of notified neighbourhoods were not revised at all. That last figure is the one that gets left out of the headlines, and it is the reason the impact is so uneven across the city.

The mechanic matters more than the percentage. Stamp duty in Haryana is charged on whichever is higher: the value written in your agreement, or the government's collector rate for that property. In most of luxury Gurgaon the market price already sits well above the circle rate, so the agreement value is what you pay duty on and a circle rate revision changes nothing for you. Where it bites is the corridor where the collector rate was lagging the market and has now been pulled up to meet it — because there, the statutory base you pay on genuinely rises.

That is why the sharpest increases landed in New Gurgaon. Sectors 104 to 115 saw collector rates move from roughly ₹4,444–4,889 to ₹7,347–7,778 per sq ft, a jump of about 62 to 67%, with group housing proposed to move from ₹4,000 to ₹7,000. Commercial land along the Dwarka Expressway was revised up to around ₹22,750 in places, a rise of up to 75%. By contrast Golf Course Road moved an average of 10 to 20%, Sohna Road about 10%, and established locations such as Sector 29 around 15%. Some of these figures were notified as proposed rather than final, so confirm the current rate for your specific sector before you sign anything.

Now the arithmetic buyers actually need. Haryana charges stamp duty at 7% for a male owner, 5% for a female owner and 6% for joint ownership, plus a registration fee of 1% of value with a minimum of ₹1,000. So your total statutory outgo is roughly 8%, 6% or 7% depending on how the title is held. On a ₹3 crore purchase that is about ₹24 lakh in a man's name, about ₹18 lakh in a woman's name, and about ₹21 lakh jointly. A ₹6 lakh difference, decided entirely by whose name goes on the deed.

That is a legitimate and widely used saving, not a loophole, and it is worth raising before the builder's documentation team fills in the form rather than after. The one thing to think through is that the registered owner is the owner — for succession, for a future sale and for capital gains — so the decision should suit your family's position and not only this transaction. Where ownership is joint, the proportions should be recorded, because they govern how a future gain is split.

Two further consequences people miss. The collector rate also sets a floor for income tax purposes: where a transaction is recorded below it, the difference can be treated as income in the hands of both buyer and seller, so there is no advantage in understating a price in a revised sector. And a higher circle rate raises the base on which your eventual capital gain is computed — relevant if you are buying to exit in five years rather than to live.

The practical summary for a Gurgaon purchase today: budget 8% of value for statutory costs rather than the 6% people quote from memory, check the current collector rate for your exact sector rather than the city average, consider female or joint ownership deliberately rather than by default, and treat New Gurgaon and the Dwarka Expressway sectors as the places where the revision genuinely changed the number. On Golf Course Road, it mostly did not.

Full article ↗
Gurgaon · Market Trends

A third of new Gurgaon homes now cost over ₹2.5 crore. What if your budget is below that?

NCR is simultaneously India's most luxury-weighted market and one that still launches a third of its homes at the bottom. The squeeze is in the middle, where most buyers actually are.

ANAROCK's Q3 2026 numbers describe an NCR market shaped like a barbell. Of everything launched in the quarter, 62% was priced above ₹1.5 crore and 34% above ₹2.5 crore — the highest luxury and ultra-luxury share of any of India's top seven cities. At the same time 33% of launches sat in the affordable and lower-mid bands. Weight at both ends, and comparatively little between them.

Hold that against Bengaluru, which launched 52% of its homes above ₹1.5 crore and just 1% in the affordable and lower-mid bands. Bengaluru has effectively stopped building at the bottom. NCR has not — it has kept a third of its supply there while simultaneously pushing a third into the ₹2.5 crore-plus band. These are two genuinely different market structures, and they call for different buying strategies even though the headline price per square foot is similar: ₹9,980 in NCR against ₹9,600 in Bengaluru.

If your budget is ₹1.5 to ₹2.5 crore in Gurgaon, the arithmetic puts you in the thinnest part of the distribution — roughly 28% of launches, between the 62% above ₹1.5 crore and the 34% above ₹2.5 crore. You are not priced out, but you are shopping in the band where developers are launching least, and that shows up as less choice, fewer launch-stage incentives and slower movement on price than buyers one band above are being offered.

Geographically that supply sits where the land is newer: the New Gurgaon sectors, the Dwarka Expressway corridor and parts of the Southern Peripheral Road. It is worth knowing that the Haryana government's own April 2026 collector rate revision raised the circle rates in Sectors 104 to 115 by about 62 to 67%, against 10 to 20% on Golf Course Road. The state does not revise rates on a hunch; a revision of that size is a statement that recorded transaction values in those sectors have moved and the official rate had fallen behind.

That leaves three workable approaches. Buy in the repricing corridor and accept that you are taking infrastructure timing risk in exchange for entry price — the roads and the metro extensions are partly ahead of you, not behind you. Or buy resale in an established sector, where ₹2.5 crore buys a larger or better-positioned home than the same money buys new, at the cost of an older building and a less complete amenity set. Or stretch into the bottom of the luxury band, where developer discipline and build quality are more consistent and where, perversely, there is more to choose from.

What not to do is wait for the band to refill. NCR posted 12% year-on-year price growth in Q3 2026, the fastest of any major Indian market, against 10,900 launches and 13,750 units sold — a market selling more than it is launching. Inventory stands at 86,200 homes with an 18-month overhang, which is healthy rather than distressed. There is no supply wave coming to rescue the middle of this market.

The counterweight, and it is a real one: an 18-month overhang means you are not forced to decide this week either. There are 86,200 unsold homes in NCR. Take the site visits, compare the cost sheets properly, and treat any launch-day urgency as a sales technique rather than a market condition. In our experience the ₹1.5–2.5 crore buyer who moves deliberately over six weeks does materially better than the one who books on the first visit.
Full article ↗
Bengaluru · Market Trends

Bengaluru's unsold stock rose 35% — and it still has India's shortest inventory overhang

The two most alarming-sounding numbers in Bengaluru's quarter contradict each other. Reading them together is the whole skill.

Two figures from ANAROCK's Q3 2026 data describe Bengaluru, and taken separately they tell opposite stories. Unsold inventory reached 80,200 homes, up 35% year on year — the sharpest annual build-up of any city in India's top seven. Inventory overhang stood at 15 months — the shortest of any city in India's top seven. Both are accurate. Neither is the whole picture.

The resolution is in how overhang is calculated: it is unsold stock divided by the rate at which that stock is selling. Bengaluru's inventory grew quickly because the city is launching a great deal — 17,700 homes in Q3 alone, up 16% year on year. But sales grew too, reaching 16,650 units, up 9% on the previous quarter and 12% year on year. A market that launches 17,700 and sells 16,650 in the same quarter is not accumulating dead stock; it is running a large operation at near-balance.

For contrast, look at Hyderabad in the same quarter: 1,14,700 unsold homes and a 28-month overhang, nearly double Bengaluru's, on 12,950 sales. That is what a genuine supply problem looks like. Bengaluru's 80,200 unsold homes clear in a little over a year at current velocity. Hyderabad's take nearly two and a half.

What this means at the negotiating table is narrower than the 35% figure suggests. Fifteen months of overhang gives you choice, not leverage. You will find several comparable options in most corridors and you should use them to compare cost sheets properly — but you should not walk in expecting distress pricing, because the seller's position is not distressed. Average Bengaluru pricing rose 8% year on year to ₹9,600 per square foot in the same quarter the inventory figure jumped.

The composition of that inventory matters as much as its size. Just 1% of Bengaluru's Q3 launches fell in the affordable and lower-mid bands, while 52% were priced above ₹1.5 crore. The stock building up is overwhelmingly premium stock. So the choice a buyer gets is real in the ₹1.5 crore-plus segment and close to non-existent below it — which is the opposite of NCR, where 33% of launches sat in the affordable and lower-mid bands.

One figure worth watching into 2027. Launches fell 18% quarter on quarter, from 21,700 in Q2 to 17,700 in Q3. If developers keep moderating while sales hold near 16,650, the overhang tightens from an already-low base and the 8% price growth has room to continue. If launches resume at Q2 levels while sales stay flat, the 35% inventory build becomes the more important number. Right now the first scenario looks more likely, but it is a quarter-by-quarter question rather than a settled trend.

Our working position: Bengaluru in late 2026 is a well-supplied market with healthy absorption, not a market turning over. Negotiate hard in the eastern and south-eastern corridors where launches concentrate, because that is where the 80,200 actually sits. Do not expect to negotiate in the established core, where nothing is being launched and the inventory figure is irrelevant. And treat 15 months of overhang as what it is — the healthiest number in the country, reported in the same breath as the scariest one.
Full article ↗
Google reviews

Bought with us?
Tell the next buyer.

Reviews on our Google Business Profile help other buyers decide whether we are the right advisor for them. If we have helped you — or fallen short — an honest review takes a minute and says more than anything we could write about ourselves.

Call us WhatsApp us